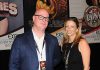
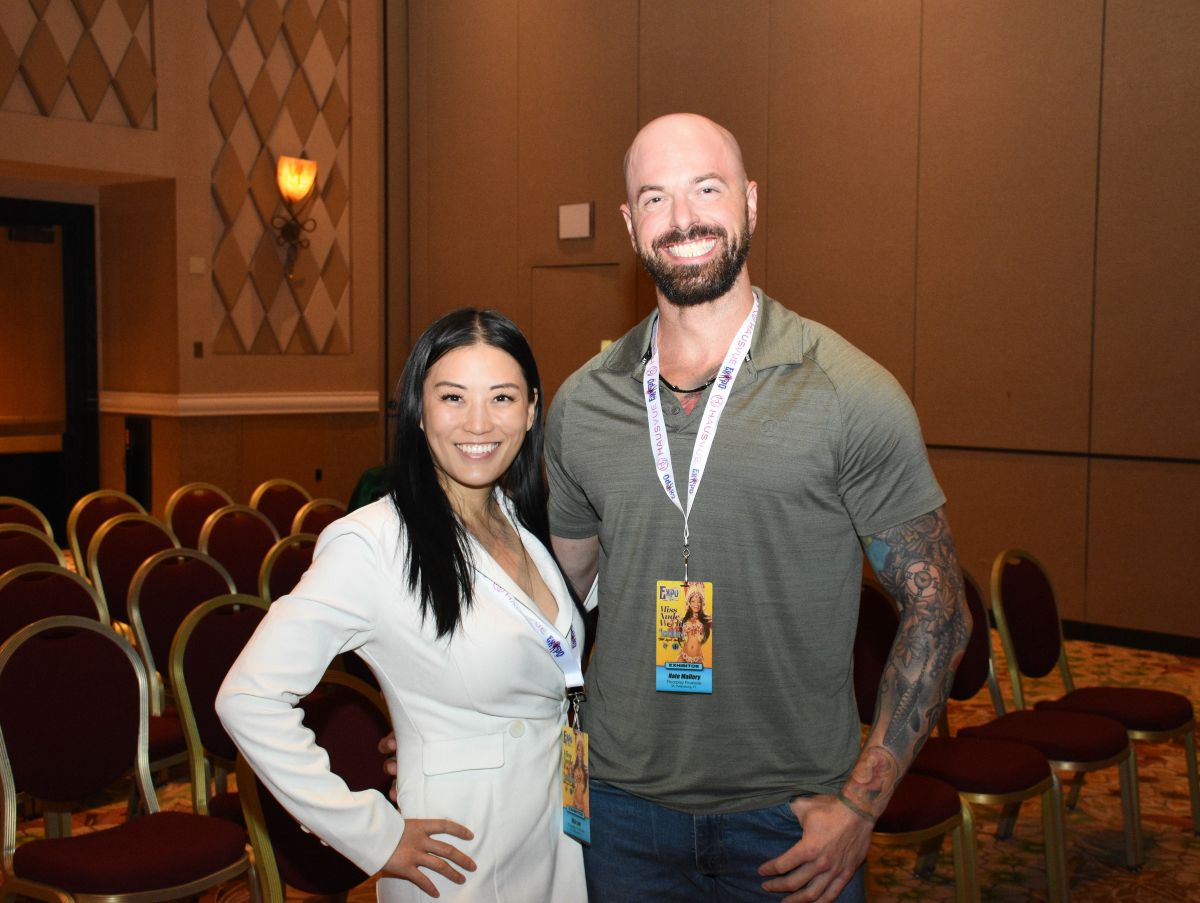
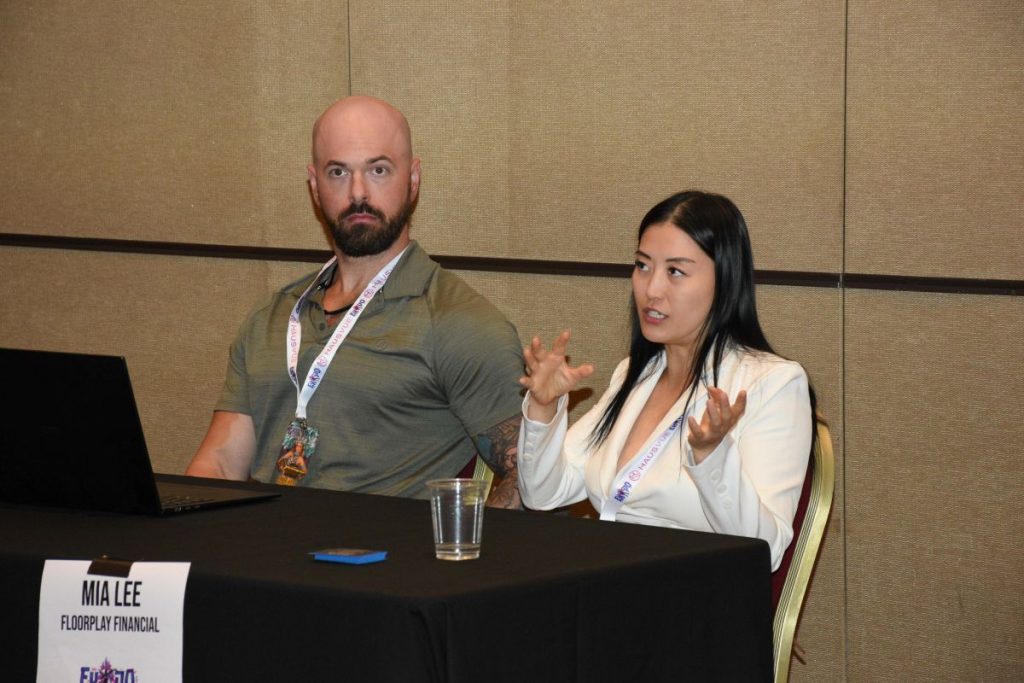
In a recap of their EXPO seminar, Mia Lee and Nate Mallory of Floorplay Financial share what entertainers need to know about taxes, deductions and the IRS.
Written by Mia Lee, CPA, and Nate Mallory, Esq., LLM
When we presented “Taxes and LLCs for Adult Entertainers” at the ED EXPO, one of the biggest themes of the seminar was simple: adult entertainers should approach their businesses like businesses. That means reporting income accurately, understanding what expenses are actually deductible, keeping a clean paper trail and planning for taxes throughout the year — not scrambling to figure everything out when the return is due.
Throughout our seminar, we addressed some of the tax questions that come up repeatedly for performers, content creators, independent entertainers and other professionals working in the adult industry. Here’s an overview of those questions.
Tell the IRS what you actually do
One of the first questions many independent entertainers encounter is deceptively simple: “What is your occupation?” Our advice is to answer truthfully.
Trying to disguise adult entertainment work as “consulting,” “event planning” or another unrelated occupation can create problems when the income and expenses reported on the return don’t match the business being described. We specifically highlighted the use of NAICS code 711510, Independent Artists, Writers and Performers and emphasized that income and deductions should be consistent with the stated trade or business.
This isn’t about making yourself look more or less “normal” to the IRS. It’s about accurate reporting.
The IRS can compare tax returns with information and patterns from businesses in the same industry. A business that reports substantial income but virtually no expenses can look unusual. The answer isn’t to invent deductions; it’s to tell the truth, claim legitimate expenses and document them.
Understand what your Schedule C is actually doing
For many independent adult entertainers, the Schedule C is where the business comes together on the tax return. We broke the form down into four major areas: gross receipts, expenses, cost of goods sold when applicable and vehicle information. Gross receipts can include income from platforms, tips, custom work and events. Business expenses can include production costs, supplies, marketing, travel, legal fees, accounting fees and other ordinary business expenditures.
The important number is ultimately net profit. That’s the amount that flows into the individual’s income tax calculation and, where applicable, self-employment tax calculation. That distinction matters because an entertainer who looks at gross income alone may dramatically underestimate the amount of money that needs to be reserved for taxes.
Don’t let estimated taxes become a surprise
Self-employment tax was another major component of the seminar. The presentation explained the basic 15.3% self-employment tax structure — 12.4% Social Security and 2.9% Medicare — and noted that one-half of self-employment tax is deductible.
For entertainers with income that doesn’t have taxes withheld from every payment, quarterly estimated taxes are particularly important.
We identified the 2026 estimated-tax payment dates as January 15, April 15, June 16 and September 15, and discussed the commonly used safe-harbor approaches: paying 100% of the prior year’s tax liability — or 110% for taxpayers above the applicable prior-year AGI threshold — or paying 90% of the current year’s tax.
One practical strategy we recommend is making the process automatic. Rather than waiting for each quarterly deadline, transfer money into a separate tax savings account every month. That turns an intimidating quarterly payment into a predictable business expense.
We also covered practical payment methods, including IRS Direct Pay, EFTPS and card payments, as well as the importance of correctly labeling estimated payments and retaining confirmation records.
The deductions that actually stick
Perhaps the most popular portion of any tax seminar is the deduction discussion — and adult entertainers have a number of legitimate business expenses that are specific to the way they work.
The presentation highlighted production expenses such as cameras, lighting, props, sets, editing, storage, software and platform fees. Depending on the facts and circumstances, work-related wardrobe or costumes, makeup, hair and health or safety supplies may also qualify when they are genuinely business-related. Other potentially deductible expenses include business travel, advertising and marketing, legal and accounting services and security expenses.
But “I use it for work” doesn’t automatically make something deductible.
Everyday street clothes, for example, generally aren’t deductible simply because they’re worn while working. The presentation also cautioned against treating purely cosmetic procedures with personal benefits as business expenses, and noted that entertainment expenses and the full cost of a home or cell phone generally aren’t deductible simply because a person has a business.
The lesson is important: don’t confuse an expense that feels connected to your business with an expense that actually qualifies under the tax rules.
Your home can be a business expense (If you qualify)
Many adult entertainers work partly or entirely from home, making the home-office deduction particularly relevant. A qualifying home office generally requires exclusive and regular business use of a dedicated room or area. Taxpayers may generally choose between an actual square-footage calculation and the IRS simplified method.
Here’s a practical example of how the deduction works: a dedicated guest room representing 15% of an apartment’s square footage, used 70% for business, could produce a 10.5% allocation of rent under the example presented.
And a home office can have another benefit: qualifying business trips beginning from the home office may allow business mileage to be deductible.
Travel, meals and vehicles require documentation
Business travel is another area where entertainers can leave substantial deductions on the table — or make mistakes by failing to document them.
During our seminar, we covered transportation and lodging for primarily business travel, business meals and vehicle expenses, emphasizing that meals are generally subject to a 50% limitation and should be documented with information such as who attended, why the meal was business-related and the date. Entertainment expenses, by contrast, are generally not deductible.
For vehicles, taxpayers generally choose between the standard mileage method and actual vehicle expenses, with a contemporaneous mileage log being essential to supporting the deduction. The presentation identified the 2026 standard mileage rate as 70 cents per mile.
Good bookkeeping is part of good tax planning
Finally, we emphasized something that isn’t particularly glamorous but can save enormous amounts of time and money: keep your books clean.
Use a separate bank account and credit card for the business rather than commingling personal and business transactions. Every month, import and categorize transactions and reconcile them to bank deposits and platform records. Keep summaries and exports, retain receipts where appropriate and maintain contracts and releases. If you pay collaborators, understand when W-9s and 1099-NECs may be required.
And don’t underestimate the value of having the right professional on your team. We recommend vetting CPAs, enrolled agents and tax attorneys based on licensing, experience with the industry, fees, scope of services and their ability to represent clients appropriately.
The bottom line from our ED EXPO seminar was straightforward: being an adult entertainer doesn’t mean you have to be afraid of the IRS. It means you need to understand your business, report it honestly, claim the deductions you’re entitled to and keep the documentation to support them.
Good tax planning isn’t about finding loopholes. It’s about making sure you’re not paying more tax than the law requires — and making sure you can prove why every number on your return belongs there.
For more information, visit floorplayfinancial.com.